What Is InsurTech and How Is It Transforming Insurance?
The rapid evolution of InsurTech and how is it transforming insurance represents one of the most significant shifts in financial services today. By blending traditional coverage with cutting-edge software, this movement is fundamentally rewriting the relationship between providers and policyholders. You will gain a clear understanding of the mechanics behind this digital transition and why it matters for your financial security.
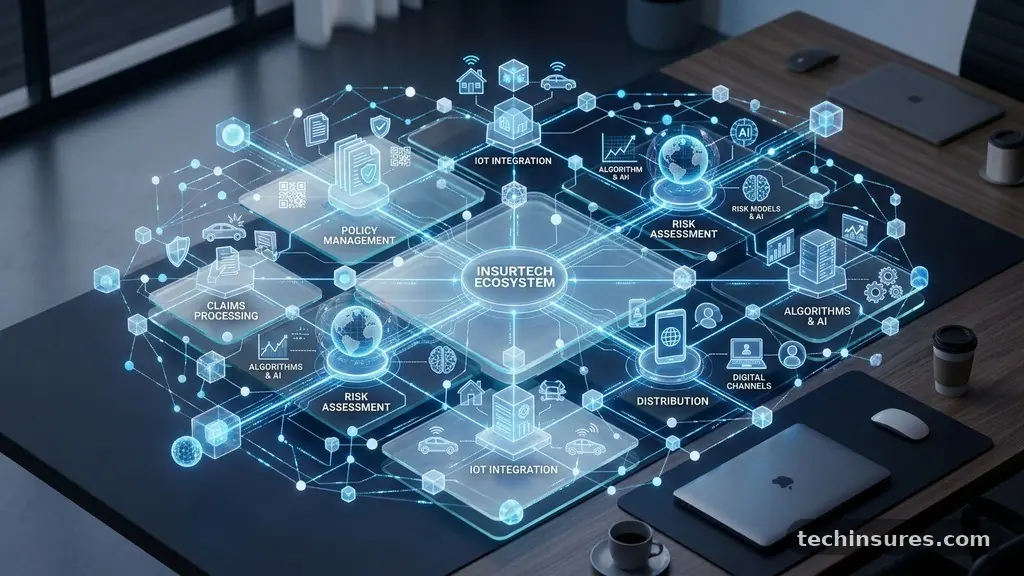
InsurTech is the application of modern technology to improve the efficiency, speed, and accuracy of the insurance industry. It operates at the intersection of finance and software engineering, replacing legacy systems with agile digital platforms. When you look at the core of the sector, it is about stripping away the friction that has historically defined the claims and underwriting process.
Defining the InsurTech Ecosystem
At its simplest, this field refers to startups and established firms that use digital tools like artificial intelligence, machine learning, and big data to optimize insurance processes. The primary goal is to lower operational costs while improving the user experience for the average customer. Instead of filing paper forms or waiting weeks for a callback, users now interact with intuitive mobile applications that handle requests in minutes.
The industry is split into two primary categories: full-stack carriers and enablers. Full-stack companies, such as Lemonade or Root, act as licensed insurers that build their own proprietary tech stacks from the ground up. Enablers, by contrast, act as service providers that sell software to traditional insurance giants to help them modernize their existing legacy infrastructures.
This distinction is crucial because it shows that the sector is not just about disruption through new startups. It is also about a massive wave of internal transformation within century-old corporations. By adopting these digital tools, massive firms are attempting to remain competitive against leaner, more technologically advanced newcomers that prioritize speed above all else.
Data-Driven Risk Assessment
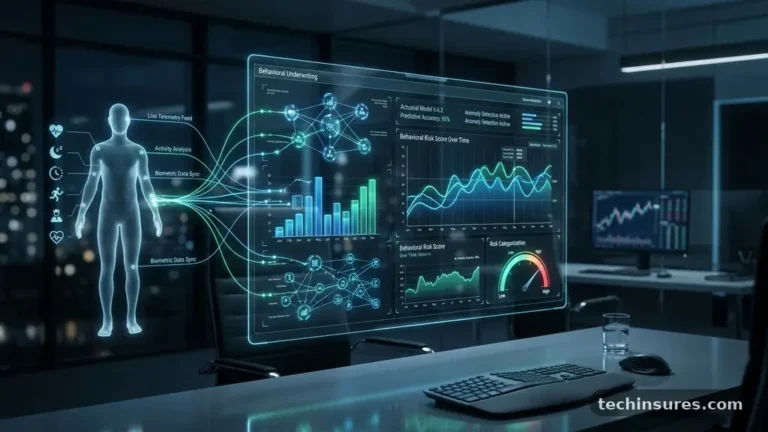
One of the most profound ways technology is changing the sector is through the use of granular data for risk assessment. Traditional models relied on broad demographic buckets to calculate premiums, often resulting in inaccurate pricing for individuals who did not fit the “average” mold. Modern platforms now ingest thousands of data points to create highly personalized risk profiles.
For example, telematics devices in vehicles can monitor braking patterns, speed, and time of day to determine a driver’s actual risk level. This shifts the focus from static historical data to real-time behavioral data. If you are a safe driver, you pay less, regardless of your age or zip code, which creates a more equitable pricing environment.
This shift extends to health and life insurance as well, where wearable devices provide insights into physical activity levels. By incentivizing healthy habits through lower premiums, insurers move from being passive payers of claims to active partners in risk mitigation. This proactive stance reduces the overall likelihood of a claim, which benefits both the policyholder and the provider’s bottom line.
Automating the Claims Process
The claims experience has historically been the most painful part of the insurance journey for customers. Historically, you had to document damages, fill out lengthy forms, and wait for a human adjuster to conduct an in-person inspection. Today, computer vision and automated workflows have drastically reduced the time required to settle simple claims.
Many modern platforms allow you to upload photos of property damage or an auto accident directly to an app. AI algorithms then analyze the images to estimate the cost of repairs in real-time. This can reduce the time between an incident and a payout from several weeks to just a few hours in many standard scenarios.
Beyond speed, automation reduces the potential for human error and administrative overhead. By removing manual data entry from the equation, companies can process thousands of claims simultaneously without increasing their headcount. This efficiency gain is passed on to the consumer in the form of lower premiums and more accessible service options.
Comparison of Traditional vs. Modern Claims
| Feature | Traditional Insurance | Modern InsurTech |
|---|---|---|
| Processing Time | Days to Weeks | Minutes to Hours |
| Data Collection | Manual Paperwork | Automated/IoT Sensors |
| Adjustment | In-Person Inspection | AI/Remote Analysis |
| Transparency | Low (Hidden Processes) | High (Real-time Status) |
Personalization through Artificial Intelligence
Artificial intelligence is the engine powering the shift toward hyper-personalized policies. By analyzing vast datasets, algorithms can predict the specific coverage needs of a user based on their lifestyle and assets. This move away from “one-size-fits-all” bundles ensures that you aren’t paying for protection you don’t actually need.
Chatbots and virtual assistants are now the first line of support for millions of policyholders. These tools are available 24/7, providing instant answers to questions about policy limits or coverage details. While human agents remain essential for complex disputes, the automation of routine inquiries allows firms to scale their support operations effectively.
Furthermore, machine learning models are becoming adept at identifying fraudulent behavior patterns. By flagging suspicious claims for manual review before they are paid out, these systems save the industry billions of dollars annually. This reduction in fraud is a major factor in maintaining the long-term financial stability of the insurance sector as a whole.
The Rise of Embedded Insurance
Perhaps the most invisible but impactful trend is the rise of embedded insurance within non-insurance platforms. This happens when you purchase coverage at the exact point of sale during a transaction on a retail or travel website. Instead of visiting a separate insurance site, the coverage is integrated directly into the checkout flow.
Consider the example of buying a flight ticket online where travel insurance is offered as a single checkbox. This convenience removes the barrier to entry, making it more likely that consumers will protect their purchases. This model relies on API-driven connections that allow insurers to “plug” their products into any digital marketplace.
This trend is expanding into everything from e-commerce shipping protection to ride-sharing coverage. By meeting the customer where they are already spending money, the industry is capturing demand that would have otherwise gone unaddressed. It is a seamless integration of risk management into the fabric of daily digital commerce.
Challenges and Regulatory Hurdles
Despite the rapid growth, the industry faces significant hurdles in terms of regulation and public trust. Insurance is a highly regulated sector, and many laws were written decades ago for paper-based processes. Adapting these rules for algorithms and automated decision-making is a slow, complex process that varies by jurisdiction.
Data privacy is another major concern for both companies and consumers. As firms collect more granular information, the responsibility to secure that data becomes paramount. A single breach can destroy a brand’s reputation and lead to massive legal fines, making cybersecurity a top priority for any tech-focused insurance firm.
There is also the “black box” problem where AI models make decisions that are difficult to explain to regulators or customers. If a policy is denied based on an algorithmic score, companies must be able to justify that decision transparently. Balancing innovation with ethical standards is the defining challenge for the next decade of development in this space.
The Future of Risk Management
Looking ahead, the focus of the sector will likely shift toward predictive prevention rather than just reactive compensation. By leveraging advancements in IoT and climate modeling, companies will be able to warn policyholders of potential risks before they materialize. For example, sensors in a home could detect a slow water leak and alert the owner to stop a major flood before it happens.
The National Association of Insurance Commissioners provides resources on how state regulators are adapting to these technological shifts. As these systems become more sophisticated, the role of the insurer will evolve from a financial safety net to a proactive partner in loss prevention. This transformation will fundamentally change how we view the value of our policies.
Key Areas of Future Innovation
- Predictive Analytics: Using climate data to warn homeowners of severe weather risks in real-time.
- Cyber-Insurance: Developing specialized coverage for digital assets and data breaches for small businesses.
- Blockchain Smart Contracts: Automating payouts for flight delays or weather-related crop losses without human intervention.
- Telehealth Integration: Combining health insurance with remote diagnostics to lower healthcare costs for everyone.
Frequently Asked Questions
What is the primary difference between a traditional insurer and an insurtech company?
Traditional insurers often rely on legacy systems and manual processes for underwriting and claims. In contrast, insurtech companies prioritize digital-first platforms, using automation and data analytics to streamline these tasks for faster, more accurate results.
Are digital-first insurance platforms safe to use?
Yes, most reputable firms in this space are subject to the same strict financial regulations as traditional carriers. You should always verify that a company is licensed to operate in your state or country before purchasing a policy.
How does data collection affect my insurance premiums?
By providing more accurate data about your habits, such as driving behavior or health metrics, you can often qualify for lower premiums. These systems reward lower-risk individuals with pricing that reflects their actual lifestyle rather than generalized statistics.
Will technology eventually replace human insurance agents?
Technology is excellent for routine tasks like renewals, simple claims, and policy questions. However, human agents remain vital for complex situations, personalized advice, and navigating difficult life transitions, so a hybrid model is the most likely future.
Final Thoughts on the Industry Shift
The ongoing evolution of InsurTech and how is it transforming insurance is not merely a trend but a fundamental redesign of how protection works in our modern world. By leveraging data to create more accurate pricing and using automation to deliver faster service, the industry is becoming more efficient and customer-centric than ever before. As you navigate your own coverage needs, you will likely encounter these digital tools more frequently in your daily life.
Staying informed about these changes will allow you to make better decisions about the products you choose and how you interact with your provider. Whether it is through an embedded offer at checkout or a telematics app on your phone, the benefits of this shift are becoming increasingly tangible for everyone. Embrace these innovations to secure your assets more effectively in an increasingly digital economy.