How Technology Is Making Insurance More Personalized
Understanding how technology is making insurance more personalized involves recognizing the shift from one-size-fits-all policies to dynamic, data-driven coverage. By leveraging real-time information and advanced analytics, insurers can now tailor premiums and benefits to individual behaviors rather than broad actuarial categories.
This evolution creates a more transparent relationship between the provider and the policyholder, fundamentally changing the insurance industry landscape. Readers will learn how specific innovations in telematics, artificial intelligence, and digital platforms are currently reshaping their personal coverage options.
The Shift Toward Behavioral Underwriting
Traditional insurance models relied heavily on static demographic data like age, gender, and zip code to estimate risk. These broad categories often penalized safe individuals who happened to belong to a statistically higher-risk group.
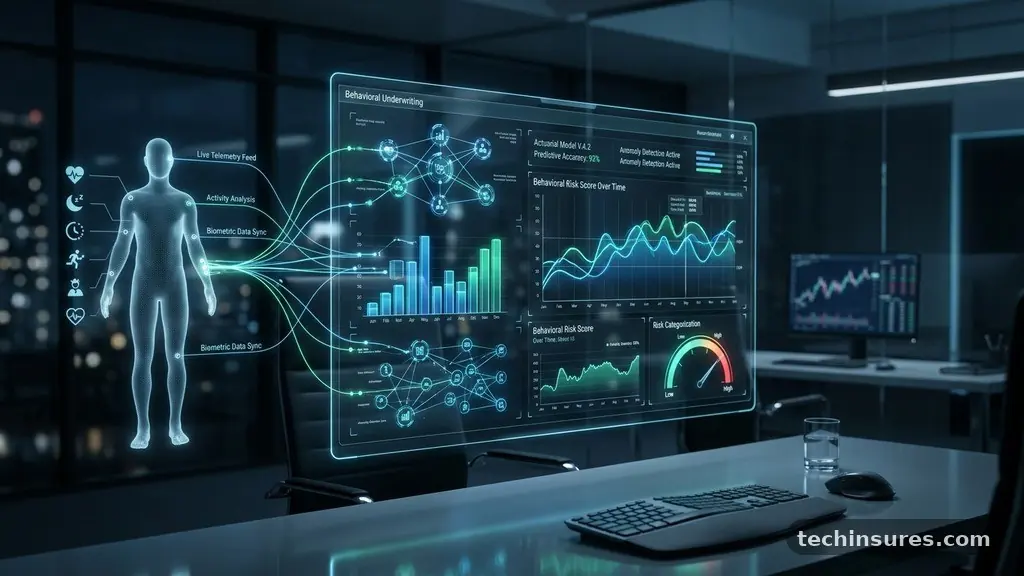
Today, technology is making insurance more personalized by moving toward behavioral underwriting. This process evaluates how you actually live your life rather than assuming your risks based on your neighbors or peers.
Telematics devices in vehicles serve as a prime example of this transition in the auto insurance sector. By monitoring driving habits such as hard braking, rapid acceleration, and speed, companies can calculate premiums based on actual performance.
If a driver consistently demonstrates safe habits, they often qualify for significant discounts that were previously unavailable. This shift incentivizes safer behavior while ensuring that premiums remain proportional to the actual risk posed by the driver.
Wearable technology is similarly disrupting the health and life insurance markets. Many providers now offer programs that track daily activity levels, heart rate, and sleep quality to provide wellness incentives.
By sharing this data, a policyholder can earn lower rates or cash rewards for meeting specific health milestones. This creates a feedback loop where the insurer acts as a partner in the customer‘s long-term health rather than just a payer for medical expenses.
Artificial Intelligence in Claims Processing
The claims experience is often the most critical moment for any policyholder, and artificial intelligence is streamlining this process significantly. In the past, filing a claim meant waiting days or weeks for manual assessment and paperwork.
Now, machine learning algorithms can analyze photos of property damage or accident scenes to provide near-instant estimates. This speed allows for faster payouts and reduces the stress associated with unexpected losses.
AI also detects anomalies that might indicate fraudulent activity, which helps keep premiums lower for the majority of honest customers. By cross-referencing claims data with historical patterns, systems can flag suspicious entries for human review without slowing down legitimate filings.
This technology ensures that the insurance ecosystem remains stable while simultaneously speeding up service for those who truly need it. The result is a more responsive system that respects the customer’s time and financial needs.
Furthermore, virtual assistants and chatbots are providing 24/7 support for routine inquiries. These tools can explain specific policy clauses or help a user update their contact information without requiring a phone call to a representative.
By automating these simple tasks, companies allow their human staff to focus on complex cases that require empathy and nuanced judgment. This combination of speed and human touch defines the modern, personalized insurance experience.
Data Analytics and Custom Coverage
The massive increase in available data is allowing insurers to create highly specific policies that were once impossible to manage. Instead of choosing from a menu of three or four standard plans, customers can now mix and match coverage options based on their unique lifestyle.
This modular approach ensures you only pay for the protection you actually need. Digital transformation in this sector has moved the industry toward a state where coverage is as dynamic as the person it protects.
For instance, homeowners insurance is becoming more granular through the use of smart home sensors. Water leak detectors and connected smoke alarms provide real-time alerts that can prevent major damage before it occurs.
Insurers often provide these devices to policyholders because the reduction in catastrophic loss benefits both parties. This proactive stance changes the relationship from purely transactional to collaborative, helping prevent disasters rather than just covering the fallout.
This data-driven environment also allows for the creation of “on-demand” insurance products. If you only need coverage for a specific trip or a short-term project, you can activate a policy via a mobile app for a few days.
This micro-insurance trend is a direct result of mobile connectivity and real-time processing capabilities. It represents the ultimate form of personalization, where the duration and scope of the policy are entirely under the user’s control.
Comparing Traditional vs. Modern Insurance
The move toward technology-driven personalization is best understood when comparing the old methods against current innovations. The table below outlines how these two approaches differ across several key operational areas.
| Feature | Traditional Insurance | Modern Personalized Insurance |
|---|---|---|
| Premium Pricing | Based on broad demographics | Based on individual behavioral data |
| Claims Speed | Days to weeks | Hours to days via AI automation |
| Engagement | Once a year at renewal | Continuous via apps and wearables |
| Policy Scope | Standardized, rigid bundles | Modular, highly customizable options |
As the data suggests, the transition is not just about fancy software; it is about changing the underlying economics of the business. By reducing administrative friction and better pricing risk, companies can offer more competitive rates. This efficiency is why many consumers are finding that their premiums are better aligned with their actual risk profiles than they were a decade ago.
The Role of Digital Platforms
Mobile apps have become the central hub for the modern insurance experience. These platforms provide a unified interface where a user can view their policy documents, file claims, and adjust coverage limits.
By putting the power of the insurance office into the user’s pocket, these apps enable a level of autonomy that was previously restricted to licensed agents. This ease of access is a fundamental component of how technology is making insurance more personalized.
These platforms also serve as educational tools that demystify complex legal language. Many apps now feature “plain language” summaries of coverage, allowing users to understand exactly what is included in their policy.
By improving transparency, insurers are building greater trust with their customer base. A well-informed policyholder is far more likely to remain loyal to a provider that offers clear, accessible communication.
The following list details some of the most common features found in modern insurance apps:
- Real-time claim tracking to see exactly where your case stands.
- Digital ID cards for quick access during medical visits or traffic stops.
- Automated premium payment reminders to prevent accidental lapses.
- Direct chat access to support teams for immediate troubleshooting.
- Risk assessment tools that suggest coverage adjustments based on life changes.
Privacy Considerations in a Data-Driven World
While the benefits of personalization are clear, the reliance on personal data raises important questions about privacy and security. Insurers must handle massive amounts of sensitive information, ranging from health records to real-time location data.
Maintaining trust requires robust cybersecurity measures and transparent communication about how data is used. Leading firms are now prioritizing “privacy-by-design” to ensure that customer data remains protected while still enabling better service.
Regulations like the General Data Protection Regulation (GDPR) and various state-level privacy laws are forcing the insurance industry to be more accountable. Insurers must clearly disclose what data they collect and, more importantly, how that data influences premiums.
This transparency is essential for the long-term viability of personalized insurance models. Consumers must feel that they are in control of their own information, even when they choose to share it for lower rates.
For a deeper look into the evolving regulatory environment regarding digital data, you can consult resources such as the National Association of Insurance Commissioners, which tracks standards for consumer protection. As technology continues to advance, the balance between innovation and privacy will remain a central theme for the industry. Companies that get this balance right will likely capture the largest share of the market in the coming years.
Future Trends in Personalized Protection
Looking toward the future, we can expect to see even deeper integration of artificial intelligence and the Internet of Things (IoT). Predictive modeling will likely shift from reactive to proactive, with insurers suggesting changes to your lifestyle or property before a risk event occurs.
This move toward “prevention-as-a-service” represents the next frontier for the industry. By preventing claims, companies can reduce costs while helping their customers live safer, healthier lives.
Blockchain technology is also poised to make waves by streamlining the verification process for claims and identity. By creating a secure, decentralized ledger, insurers can reduce the time spent on manual verification and cross-checking documents.
This could lead to a near-instantaneous settlement of simple claims, further enhancing the customer experience. The goal is to remove the friction that has historically made insurance a cumbersome and confusing industry.
As these technologies mature, the definition of “insurance” will continue to evolve. It will move away from being a static financial product and toward an active, ongoing partnership.
The companies that succeed will be those that embrace this shift, providing tools that help customers manage their risks in real-time. The era of the “set it and forget it” policy is rapidly coming to an end, replaced by a dynamic, personalized model.
Frequently Asked Questions
Does sharing my personal data always lead to lower insurance premiums?
Not necessarily. While many telematics and wellness programs offer discounts for positive behavior, the data could also reveal high-risk habits that might lead to higher premiums. It is important to review the terms of each program before opting in to ensure you understand how your data will influence your specific policy costs.
Is it true that AI is denying healthcare claims automatically?
AI is increasingly used to process claims, but it is primarily used to speed up approvals for routine procedures. When a claim is denied, it is typically because it does not meet the specific coverage criteria outlined in your policy, not because a machine acted randomly. Most companies have appeal processes that involve human review if you believe a claim was incorrectly denied.
How is technology changing the insurance industry for the average customer?
For the average customer, technology is making insurance more personalized and accessible through mobile apps and faster, automated claims processing. You no longer have to wait for an agent to manually input data or mail in physical forms. These changes lead to a faster, more transparent experience that puts you in control of your coverage.
What are the key technology trends for the insurance industry in 2026?
The key trends for 2026 include the widespread adoption of AI-driven predictive analytics, the integration of IoT devices in homes and cars, and the use of blockchain for secure, rapid claims settlements. There is also a major focus on hyper-personalization, where policies are adjusted in real-time based on the user’s current situation and needs.
Conclusion
The transition toward a more tailored insurance landscape is fundamentally shifting the power dynamic between providers and policyholders. By leveraging data and analytics, the industry is moving away from broad, one-size-fits-all solutions toward models that recognize individual circumstances.
This evolution ensures that you receive coverage that is not only cost-effective but also aligned with your specific lifestyle needs. As these technologies continue to mature, the benefits of this increased transparency and efficiency will become even more apparent.
To get the most out of these advancements, consider reviewing your current policies to see if your provider offers digital tools or behavioral incentives. Engaging with these features allows you to take an active role in managing your risk profile and potentially reducing your costs.
How technology is making insurance more personalized is ultimately about empowering you to make better, more informed decisions about your financial security. Keep an eye on how your provider updates their platform, as new features could offer significant advantages for your personal coverage.