How Machine Learning Is Being Used in the Insurance Industry
Understanding how machine learning is being used in the insurance industry reveals a shift from reactive protection to proactive risk mitigation. Insurance companies are increasingly leveraging advanced data models to automate complex decision-making, resulting in faster service and more accurate pricing. By processing vast datasets that were previously unmanageable, these systems identify patterns humans might miss entirely.
This evolution is reshaping the relationship between providers and their policyholders, moving toward a model of personalized coverage. Readers will learn how these algorithmic tools function, the specific benefits they provide, and what the future holds for the sector as these technologies continue to mature.
Real-Time Risk Assessment and Pricing
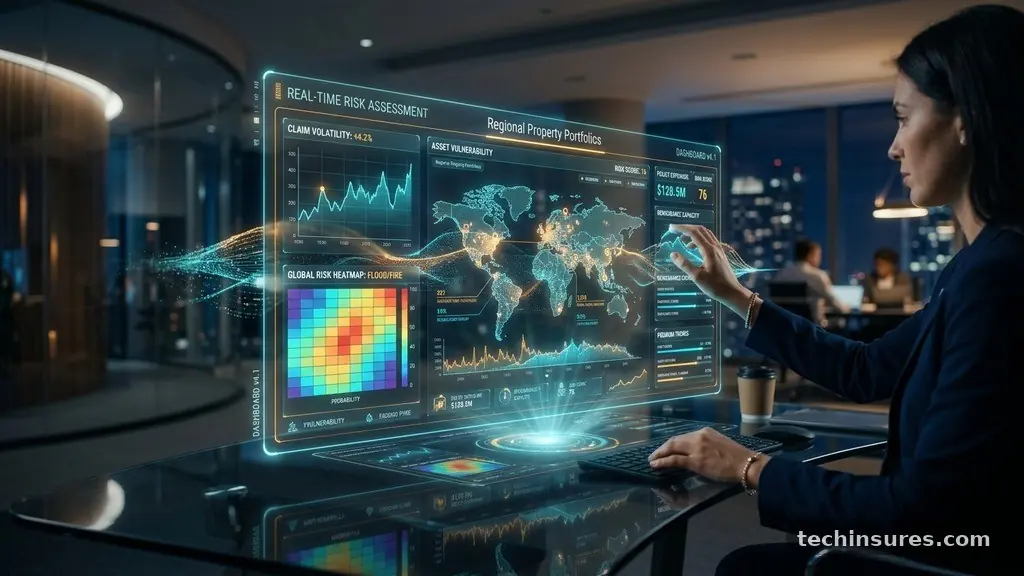
The core of how machine learning is being used in the insurance industry centers on the ability to calculate risk with unprecedented granularity. Traditional actuarial science relied heavily on historical averages and broad demographic categories. Today, machine learning models ingest thousands of variables simultaneously to create dynamic risk profiles for individual applicants.
Instead of waiting for an annual renewal to adjust premiums, insurers can now update pricing based on real-time behavior. For instance, telematics devices in vehicles track braking patterns, speed, and time of day, feeding this data directly into predictive models. This allows companies to offer usage-based insurance, where safe drivers pay significantly less than those who exhibit high-risk habits on the road.
This shift helps mitigate the adverse selection problem that has historically plagued the sector. By accurately pricing risk at the individual level, insurers can attract safer customers while maintaining profitability. The following table highlights the differences between traditional and machine learning-driven pricing models:
| Feature | Traditional Model | Machine Learning Model |
|---|---|---|
| Data Scope | Limited to static variables | Unlimited, dynamic, and external |
| Update Frequency | Annual or semi-annual | Real-time or continuous |
| Risk Accuracy | Broad group-based averages | Highly individualized predictions |
| Efficiency | Manual, time-intensive | Automated, instant processing |
Transforming the Claims Process
Claims processing is arguably the most visible area where machine learning is being used in the insurance industry to improve customer satisfaction. Historically, filing a claim was a slow, paper-heavy process involving multiple manual checks. Now, computer vision and automated document processing can handle routine claims in minutes rather than weeks.
When a policyholder uploads photos of property damage, neural networks analyze the images to estimate the cost of repairs instantly. These models are trained on millions of historical images to identify the severity of damage to structures or vehicles. This automation reduces the administrative burden on adjusters, allowing them to focus on complex or suspicious claims that require human intervention.
Fraud detection has also seen a massive upgrade through these automated systems. Machine learning algorithms flag anomalies in claim submissions that deviate from typical patterns, such as inconsistent timestamps or suspicious geographic locations. By identifying potential fraud early, insurers save billions in payouts annually while keeping premiums lower for honest customers.
Personalization and Customer Engagement
Insurers are moving away from one-size-fits-all products to highly personalized experiences. Machine learning identifies individual needs by analyzing past interactions, social data, and life events. This allows companies to suggest relevant coverage additions or discounts exactly when a customer needs them.
For example, if a customer buys a new home, the system can automatically suggest specific riders for high-value items or flood insurance based on the property’s location. This proactive engagement builds trust and increases customer retention rates. The goal is to act as a partner in risk management rather than just a provider of indemnity.
Companies also use chatbots and virtual assistants powered by natural language processing to handle routine inquiries. These tools provide 24/7 support, answering questions about policy terms or coverage limits without the need for a call center. This efficiency frees up human staff to handle sensitive issues that require empathy and nuanced judgment.
The Role of Predictive Analytics in Underwriting
Underwriting is the gatekeeper of the insurance business, and machine learning has fundamentally changed how this function is performed. By integrating external data sources, such as satellite imagery for property risk or wearable health data for life insurance, models provide a 360-degree view of the applicant. This allows underwriters to make faster, more informed decisions that align with the company’s risk appetite.
In life insurance, for example, some providers now allow applicants to opt into digital health data sharing. Instead of waiting for weeks for a medical exam, the insurer evaluates health trends derived from fitness trackers. This creates a smoother application process and a more accurate assessment of long-term health risks.
* Improved speed: Drastically reducing the time from application to policy issuance.
* Data integration: Combining internal history with external, real-time data streams.
* Risk segmentation: Identifying niche market opportunities previously hidden by broad categorization.
* Reduced bias: Standardizing decision-making through objective, algorithmically-backed criteria.
Managing New Risks for the Digital Age
As technology advances, so do the risks that people and businesses face. Machine learning is being used in the insurance industry to develop products for emerging fields like cyber security and autonomous vehicle operation. Because these areas lack deep historical data, traditional models fail to provide accurate pricing.
Machine learning helps fill these gaps by simulating various scenarios to predict the probability of cyberattacks or software failures. This allows insurers to offer coverage for risks that were once considered uninsurable. For more information on how technology influences risk standards, you can review the National Bureau of Economic Research findings on market trends.
These models are constantly learning, updating their parameters as new incident data flows in. This adaptability is critical in a world where technology evolves faster than the regulatory environment. It ensures that insurance remains a reliable safety net for innovation and economic growth.
Ethical Considerations and Algorithmic Fairness
The use of complex algorithms raises questions about transparency and fairness in the insurance sector. It is essential for providers to ensure their models do not inadvertently discriminate against protected groups. Regulators are increasingly scrutinizing how these systems arrive at their conclusions to prevent biased outcomes.
Insurers must maintain “explainable AI” to comply with legal requirements and maintain public trust. This means the models must be able to document exactly which factors contributed to a specific pricing or coverage decision. If a model cannot explain its reasoning, it creates significant legal and reputational risk for the company.
Bias can creep into models through historical data that reflects past societal inequities. Data scientists are now tasked with testing for these biases during the development phase. By implementing rigorous auditing frameworks, companies can harness the power of machine learning while ensuring equitable treatment for all applicants.
Future Trends and Long-Term Impact
The future of the insurance industry will be defined by the integration of AI into every aspect of the business. We will see a shift toward “predict and prevent” models where the primary goal is to avoid losses before they occur. For instance, smart home sensors might alert a homeowner to a water leak before it causes major damage to the property.
As these technologies become more accessible, smaller insurance firms will also be able to implement them to compete with larger incumbents. Cloud-based machine learning platforms make high-level analytics available without the need for massive on-premise infrastructure. This democratization of technology will likely lead to a more diverse and innovative market.
Ultimately, the goal is to create a more resilient society where risks are understood and managed in real-time. As the industry matures, the focus will likely move toward greater transparency and collaboration between tech developers and traditional insurers. This evolution will lead to more tailored, affordable, and effective protection for everyone.
Frequently Asked Questions
Is machine learning replacing insurance adjusters and underwriters?
No, it is not replacing them but rather augmenting their capabilities. While routine tasks are automated, complex cases still require the judgment, empathy, and experience of human professionals to resolve effectively.
How does machine learning improve fraud detection?
Algorithms can scan millions of claims in seconds to identify patterns and anomalies that indicate potential fraud. By flagging these inconsistencies, the system alerts human investigators to focus on high-risk cases that merit deeper scrutiny.
Can machine learning remove bias from insurance pricing?
It has the potential to make pricing more objective by relying on data-driven metrics rather than human prejudice. However, designers must actively audit their models to ensure that historical data does not contain and perpetuate existing biases.
What is the biggest challenge of using AI in insurance?
The primary challenge is balancing innovation with regulatory compliance and data privacy. Insurers must ensure their models are transparent, explainable, and secure while protecting the sensitive personal information of their policyholders.
Will premiums become cheaper because of machine learning?
For many customers, especially those who demonstrate lower risk through their behavior, premiums can become more competitive. By reducing operational costs and improving risk accuracy, insurers can pass savings on to the consumer in a more efficient market.
Conclusion
How machine learning is being used in the insurance industry is a clear indication that the sector is moving toward a more data-driven and responsive future. By embracing these tools, companies are finding ways to provide more precise coverage while reducing the friction that often frustrates policyholders. The ability to process vast amounts of data in real-time allows for a level of customization that was simply impossible a decade ago.
As you explore how these technologies might affect your own policies, consider how your data usage and personal habits can play a role in your risk profile. While the technology continues to evolve, the core mission of insurance remains the same: providing security and peace of mind. Keeping up with these trends will ensure you are better positioned to benefit from the shifting landscape of modern coverage.