How Digital Claims Processing Is Changing Insurance Services
Understanding how digital claims processing is changing insurance services requires looking at the shift from paper-heavy, manual workflows to instantaneous, data-driven decision-making. By leveraging advanced automation and real-time connectivity, insurers are fundamentally altering the speed and accuracy of the settlement lifecycle. This transformation moves the industry away from weeks of waiting toward a model defined by immediate resolution and transparent communication.
As policyholders increasingly demand modern, app-based interactions, firms that fail to adapt risk losing their competitive edge in a fast-paced market. This article explores the specific technologies driving these shifts and the tangible benefits they offer to both the provider and the customer.
Speeding Up the Settlement Lifecycle
The most immediate impact of digital adoption is the drastic reduction in the time required to settle a claim. Historically, a simple vehicle accident or property damage report involved physical mail, multiple phone calls, and manual entry of handwritten forms.
Today, the process often begins the moment an incident occurs, thanks to mobile applications that allow users to upload photos directly from the scene. These images are instantly analyzed by computer vision algorithms that can estimate repair costs with impressive accuracy.
When a system can verify damages without waiting for an adjuster to travel to a site, the administrative bottleneck vanishes. Many insurers now utilize “straight-through processing” for low-complexity claims, where software handles the approval and payment initiation without human intervention.
This shift moves the industry away from a model where an adjuster’s schedule dictates the pace of service. Instead, the workflow is governed by the speed of data ingestion and automated validation rules.
The Role of Data and Predictive Analytics
Modern claims management relies heavily on the quality and volume of data collected during the intake phase. By integrating external data sources—such as weather reports, historical repair records, and even telematics from connected vehicles—insurers build a more comprehensive profile of the loss.
This predictive capability allows carriers to identify fraudulent behavior patterns far earlier in the process than traditional auditing ever could. It also helps in segmenting claims based on complexity, ensuring that human experts spend their time on high-value, nuanced cases.
Predictive models are also refining the way insurers allocate internal resources. Rather than assigning claims sequentially, systems can route them to the specific adjuster best suited to handle the unique circumstances of the incident. This intelligent distribution leads to faster resolutions and more accurate settlements.
The reliance on data ensures that decisions are grounded in objective evidence rather than subjective assessment. It creates a more consistent experience for the policyholder, who can trust that their case is being evaluated against industry-wide standards.
Enhancing the Customer Experience
Digital transformation is not just about backend efficiency; it is about providing a frictionless experience for the policyholder. Clients today expect the same level of service they receive from e-commerce platforms or banking apps.
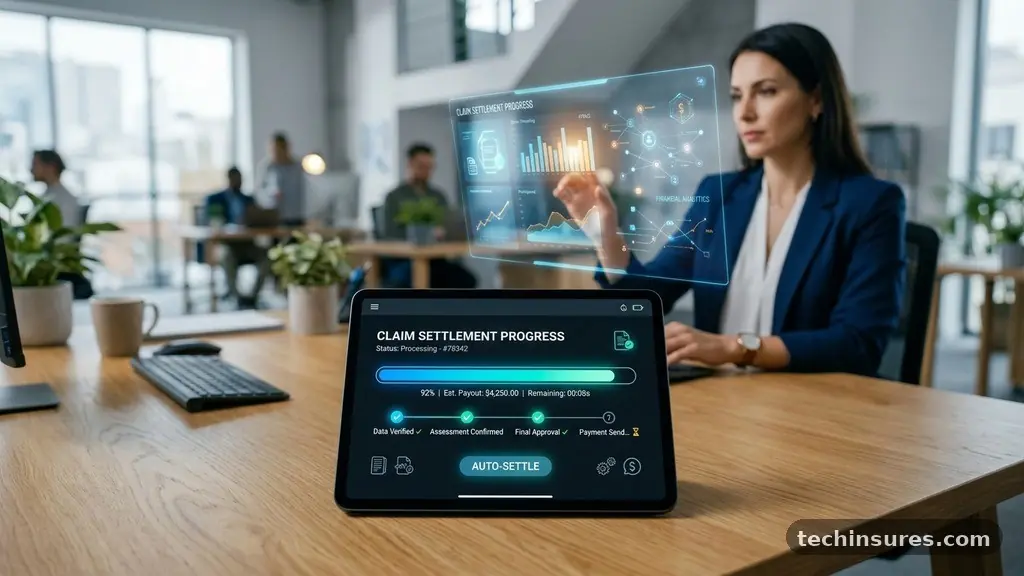
They want to track the status of their insurance claims in real-time, receive push notifications, and chat with support agents through secure messaging portals. This level of transparency builds trust and reduces the anxiety that typically accompanies a stressful loss event.
Self-service portals have become a cornerstone of this new operational paradigm. When a customer can initiate, track, and provide documentation for their file through a single interface, their reliance on call centers drops significantly. This shift reduces the operational load on staff while simultaneously empowering the customer.
A transparent, digital-first approach transforms a traditionally adversarial or bureaucratic process into a helpful service. When policyholders feel informed throughout the life of their file, their long-term loyalty to the insurer increases.
| Process Phase | Traditional Method | Digital Method |
|---|---|---|
| First Notice of Loss | Phone call, paper form | Mobile app, image upload |
| Damage Assessment | In-person adjuster visit | Computer vision, remote video |
| Approval | Manual review by team | Automated rule engine |
| Settlement | Physical check via mail | Instant digital transfer |
Automating Fraud Detection and Risk Mitigation
Fraud remains a significant drain on the insurance industry, costing billions annually and driving up premiums for honest customers. Advanced automation is changing the game by flagging inconsistencies in real-time that would previously have gone unnoticed by human eyes.
By comparing incoming claim data against massive databases of past activity, algorithms can detect suspicious links, such as duplicate submissions or patterns associated with known fraud rings. This proactive stance protects the financial integrity of the insurance pool.
Automation also improves accuracy by minimizing the human error inherent in manual data entry. When information is pulled directly from digital sources—such as police reports or repair shop software—the risk of typos or misclassification is effectively eliminated.
This precision ensures that payments are calculated correctly and processed without unnecessary delays. The result is a more robust, secure environment for both the insurer and the policyholders they serve.
The Future of Adjuster Roles
The rise of artificial intelligence does not signal the end of the human claims adjuster; rather, it marks a shift in their primary responsibilities. As routine and low-stakes tasks are handled by software, human professionals are freed to focus on high-touch, complex cases that require empathy and nuanced judgment.
An adjuster’s role is evolving from a data-entry clerk into a specialized consultant who manages the most difficult situations. This change allows for deeper human-to-human connection when it matters most, such as during catastrophic events or complex liability disputes.
Professional development for adjusters now includes training in digital literacy and data interpretation. Understanding how to collaborate with AI tools is becoming a critical skill set in the modern workforce. This collaboration creates a hybrid model where technology handles the volume and humans handle the value.
The Insurance Information Institute provides further context on these evolving industry standards and how they affect the broader market. This evolution ensures that the human element of insurance remains at the heart of the service, supported—not replaced—by technology.
Key Components of Digital Transformation
To successfully implement these changes, insurers must invest in a layered technological stack. This includes cloud-based infrastructure that allows for secure, remote access to files and collaborative tools for cross-functional teams.
It also requires the integration of APIs that connect the insurer’s systems with third-party vendors, such as repair shops, healthcare providers, and legal firms. These connections are what allow for the seamless flow of information that drives the digital claims process.
- Cloud-based storage for instant access to documentation
- Computer vision for automated damage assessment
- Telematics and IoT sensors for real-time risk data
- AI-driven chatbots for 24/7 customer support
- Blockchain for secure and immutable record keeping
Without these interconnected systems, an insurer is essentially operating with disparate silos of information. The goal of digital transformation is to break down these barriers so that every stakeholder has a single, accurate view of the claim status.
This unity of information is the foundation upon which all other improvements are built. It is the engine that drives the speed and efficiency that customers now demand.
Overcoming Implementation Challenges
Transitioning to a fully digital workflow is not without its hurdles. Legacy systems often present significant technical debt, making it difficult to integrate modern software without a complete architectural overhaul.
Additionally, there is the challenge of organizational culture; employees who have worked in traditional systems for decades may be resistant to new digital tools. Successful firms approach this by focusing on change management and providing robust training programs.
Data privacy and security are also paramount concerns. As insurers collect more granular data, they must ensure that their systems are fortified against cyber threats and compliant with international regulations.
Building customer trust in digital security is just as important as the efficiency of the software itself. By prioritizing transparent data usage policies, insurers can demonstrate that their digital shift is designed to protect the customer as much as it is to streamline operations.
Frequently Asked Questions
Is it true that AI is denying healthcare claims?
AI is increasingly used to review claims, but it typically acts as a decision-support tool rather than an autonomous judge. It can flag claims that lack sufficient documentation or do not meet specific policy criteria. However, human oversight remains a standard practice for final denials to ensure that clinical nuances are respected and that the decision aligns with contractual obligations.
Will claims adjusters be replaced by AI?
While AI is replacing the manual labor associated with simple, routine claims, it is not replacing the need for adjusters. Instead, the role is shifting toward complex cases that require human empathy and critical thinking. AI handles the data-heavy lifting, allowing adjusters to focus on high-value interactions and difficult decision-making processes.
How does digital processing benefit the policyholder?
The primary benefit is speed. Digital tools allow for near-instant submission of information and faster approval times. Policyholders also enjoy greater transparency, as they can track their claim status in real-time through mobile apps rather than waiting for updates via phone or mail.
What are the biggest risks of digital claims processing?
The main risks include cybersecurity threats, data privacy concerns, and the potential for technical errors in automated systems. Insurers must invest heavily in secure architecture and rigorous testing to ensure that their digital processes are resilient and accurate. Maintaining human oversight for critical decisions is also a necessary safeguard.
Conclusion
The evolution of how digital claims processing is changing insurance services represents a permanent shift in the industry landscape. By embracing automation, data analytics, and mobile-first interfaces, providers are creating a more efficient and transparent ecosystem for everyone involved. This move away from manual, paper-based workflows is not merely a technological upgrade; it is a fundamental improvement in how value is delivered to the customer.
As these tools continue to mature, we can expect even greater precision and speed in the settlement process. Staying informed about these changes allows policyholders to better navigate their interactions with insurers, ensuring they receive the full benefit of these modern advancements. Embracing these digital capabilities is the most effective way for the industry to maintain trust and relevance in an increasingly connected world.